When rent is due, a car needs repairs, or an unexpected bill shows up, most New Yorkers face a familiar crossroads: swipe the credit card, call a payday lender, or find another way. That’s exactly where pawn shop loans NYC residents have been quietly relying on for decades come into the picture, offering a fast, straightforward path to cash that doesn’t saddle you with crushing interest rates or a credit check that haunts you later.
The Debt Trap Nobody Warns You About
Payday loans sound simple until you read the fine print. Annual percentage rates on payday loans regularly hit 300% to 400% in New York, and that’s on the conservative end. Credit cards aren’t much kinder when you’re carrying a balance month to month. What starts as a $500 emergency can snowball into a debt that takes years to pay off.
A collateral-based loan from a licensed pawnbroker works on an entirely different logic. You bring in an item of value, a gold chain, a designer watch, a diamond ring, and the shop lends you money against it. The interest rate is regulated by New York State law, which caps what pawnbrokers can charge. You know exactly what you owe before you walk out the door. No surprises, no rollovers, no collection calls.
Many customers who’ve used this option describe the relief of knowing the terms upfront as one of the biggest differences compared to other short-term borrowing. That clarity matters when you’re already stressed about money.
Your Credit Score Stays Out of It Completely
One of the most underappreciated advantages of borrowing against your valuables is that your credit history is completely irrelevant. Pawnbrokers don’t pull your credit report. They don’t report to credit bureaus. The loan is secured entirely by the item you bring in, that’s the collateral, and that’s all that matters.
This makes collateral lending genuinely useful for people who’ve had financial setbacks in the past, recent immigrants building credit from scratch, or anyone who simply doesn’t want a hard inquiry showing up on their report. In a city where the cost of living is relentless and financial hiccups are common, having a borrowing option that sidesteps the credit system entirely is more valuable than most people realize.
If you repay the loan within the agreed term, you get your item back. If you can’t, the shop keeps the item to recover the loan, but your credit score is untouched, and you owe nothing further. There’s a clean exit built into the structure that payday lenders and credit card companies simply don’t offer.
What You Can Actually Bring In, and What It’s Worth
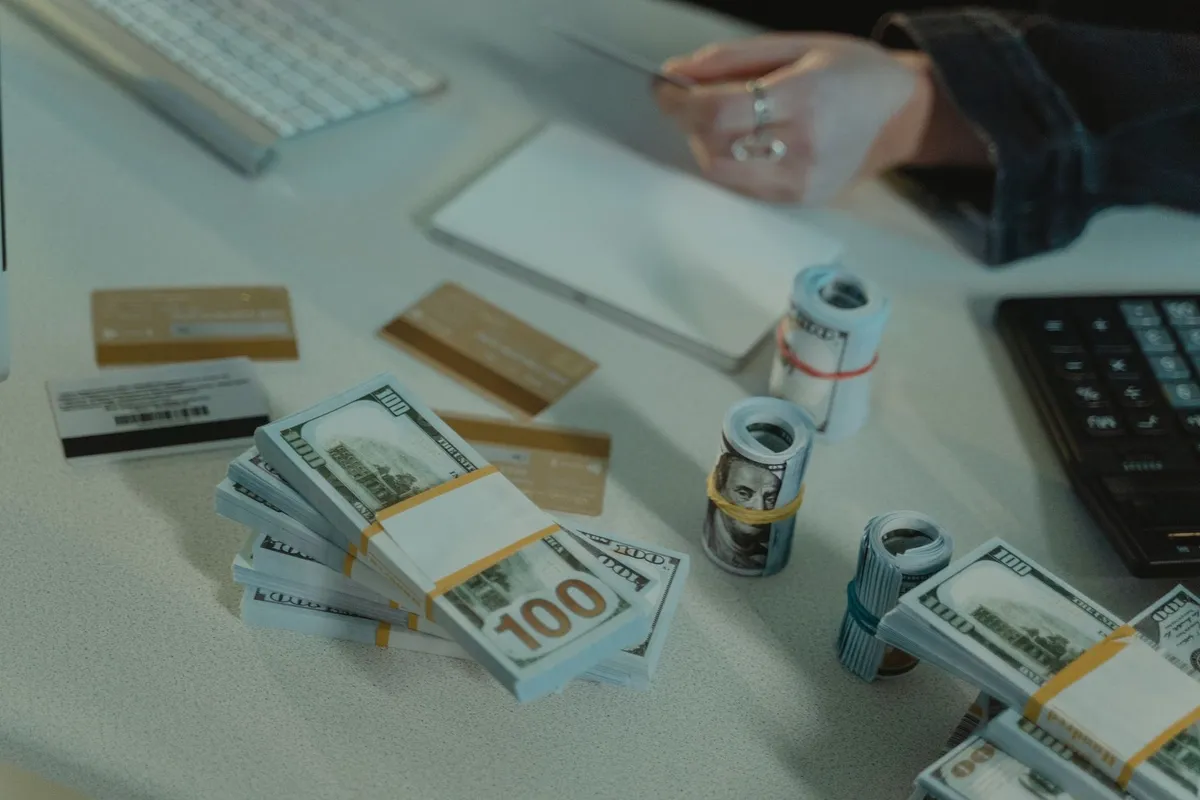
People are often surprised by the range of items that qualify for a collateral loan. Gold and silver jewelry are the most common, and for good reason, precious metals hold value reliably and are easy to assess. But luxury watches, diamond jewelry, and even coins can all serve as collateral for a meaningful loan amount.
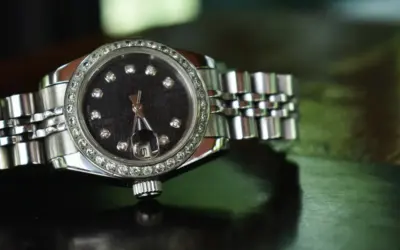
If you’re thinking about using a pawn shop in NYC for the first time, it helps to understand how items get valued. A licensed appraiser looks at the metal content, gemstone quality, brand, and current market conditions. A Rolex in good condition, for example, can command a substantial loan, far more than most people expect. If you’re curious about what a luxury timepiece might be worth, what to expect when pawning luxury watches in NYC is worth reading before you come in.
Gold jewelry is another strong performer. The spot price of gold has remained strong, which means even older or broken pieces can yield a solid loan offer. The key is bringing in items that have genuine intrinsic value, not sentimental value, but market value. A gemologist or experienced appraiser can tell the difference in minutes.
How to Get the Most From a Collateral Loan
Walking in prepared makes a real difference. Clean your jewelry before bringing it in, not to deceive anyone, but because a well-presented item is easier to assess accurately. Bring any original paperwork, boxes, or certificates you have for watches or fine jewelry. Documentation adds credibility and often bumps up the loan offer.
Know roughly what your item is worth before you arrive. A quick search of recent sales for comparable pieces gives you a realistic baseline. You don’t need to become an expert overnight, but walking in with zero information puts you at a disadvantage in any negotiation.
Ask questions. A reputable shop will explain exactly how the loan is calculated, what the monthly interest rate is, and what the redemption process looks like. At NYC Pawn Shopsthe team has years of experience working with New Yorkers in exactly these situations, the process is transparent, and there’s no pressure to accept an offer you’re not comfortable with.
One more thing worth knowing: you can often extend or renew a loan if you need more time. Paying the interest to extend your loan term keeps your item in the shop while you get your finances sorted. It’s not ideal, but it’s far better than defaulting on a payday loan that keeps compounding.
Short-term financial pressure is a reality for millions of New Yorkers. A collateral loan won’t solve every problem, but it offers something rare in the lending world, speed, simplicity, and a fixed cost you can plan around. That’s not nothing. In a city that moves this fast, sometimes that’s exactly what you need.
Frequently Asked Questions
What interest rate will I actually pay on a collateral loan at a NYC pawn shop?
New York State law caps the interest rates that licensed pawnbrokers can charge, so you won’t face the 300% to 400% annual rates that payday lenders routinely hit. The shop is required to tell you the exact monthly rate and total cost before you agree to anything, so you know what you owe before you walk out the door.
What happens to my credit score if I can’t pay the loan back?
Nothing, pawnbrokers don’t pull your credit report going in, and they don’t report to credit bureaus if things go sideways. If you can’t repay, the shop keeps your item to cover the loan, and that’s the end of it, no collections, no lingering debt, no mark on your credit history.
Besides gold jewelry, what kinds of items can I actually use as collateral?
Silver jewelry, diamond pieces, luxury watches, and coins are all commonly accepted, and a Rolex in good condition can bring in a substantially higher loan offer than most people expect. The key is that the item needs real market value, what something means to you personally doesn’t factor into how an appraiser prices it.
What should I bring with me to get the best loan offer on a watch or piece of jewelry?
Clean the item before you come in, and bring any original boxes, paperwork, or certificates you have, documentation regularly bumps up the offer on watches and fine jewelry. It also helps to look up recent sales of comparable pieces beforehand so you have a realistic number in your head going into the conversation.
What are my options if the loan term ends and I still don’t have the money to redeem my item?
You can pay the interest owed to extend the loan term and keep your item held at the shop while you get your finances in order. It costs you more overall, but it’s a fixed, known cost, which is a very different situation from a payday loan that keeps compounding the longer you carry it.
0 Comments